Travel insurance is one of those things you buy and hope you never need. It’s easy to skip over the fine print, especially when you’re excited about a trip and just want it sorted. I’m Mark, and along with my wife Bec, we’ve travelled to over 45 countries in the last 26 years. In that time we’ve had our fair share of insurance claims, some good, some not so good. Here’s what we’ve learned.
You won’t know how good your policy is until you need it
If you can’t afford travel insurance, you can’t afford to travel. That’s something I’ve always said and stuck to. We’ve needed it more than once. Hospital visits in Germany, Cambodia and Vietnam. A doctor in Bali. A stolen bag in Italy. Every one of those claims taught us something about how insurance actually works, not how you think it works.
Duty of care catches a lot of people out
Most policies expect you to act like a “reasonable person.” Sounds fair enough until you realize how loosely that gets applied. Leave your bag under a cafe table for two minutes and that can be called unattended.
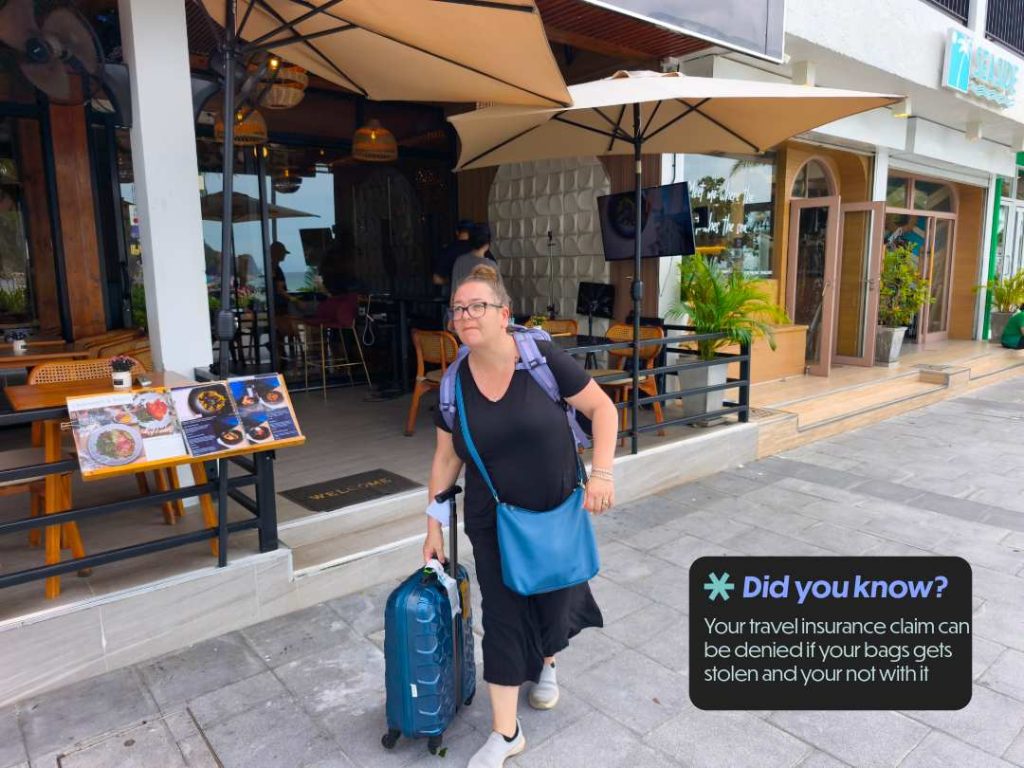
Same with a phone on a beach towel while you’re in the water. We’ve seen people knocked back on claims for exactly this. It gives the insurer room to argue you didn’t take enough care, even when it feels like common sense to us.
Even a backpack on a train luggage rack can count as unattended, no matter how close you’re sitting. We found this out when our bag was stolen in Naples. First time travellers are usually shocked by how strict this rule is applied.
Depreciation means you won’t get like for like
If something gets stolen, don’t expect a straight replacement. Insurers depreciate the value. Say your camera cost $1,200 two years ago. You might only get $800 or $900 back. It’s worth knowing this before you travel with anything expensive, because the payout is rarely what you paid.
Pre-existing conditions cover more than you’d think
This isn’t just about serious illness. High blood pressure, anxiety, even ongoing back pain can fall under this. If an insurer can link your claim back to something like that, even loosely, they can use it to deny you. Always declare everything, even things that feel minor.
Alcohol is a grey area, and not in your favour
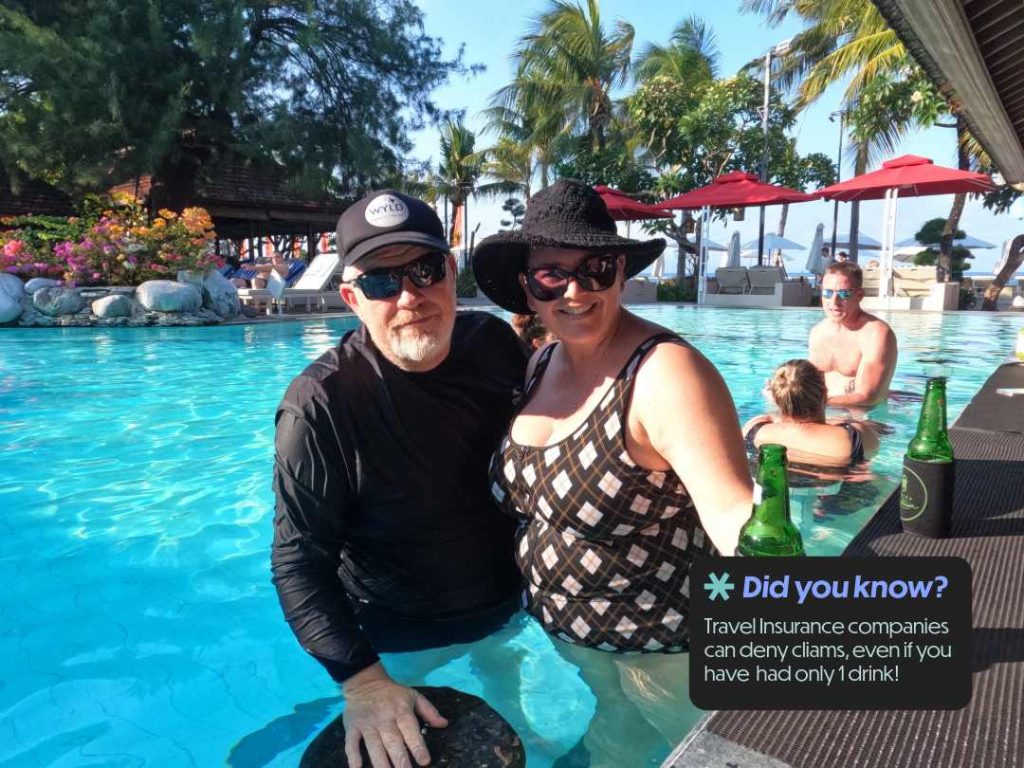
We like a cocktail at sunset as much as anyone. But most policies don’t need you to be drunk to knock back a claim. If alcohol played any part in what happened, that’s often enough. There’s no clear blood alcohol limit written down either. That’s on purpose. It gives the insurer a reason to deny your claim.
Take a photo of every receipt the moment you get it and email it to yourself. We started doing this after the Italy bag theft. It’s saved us more than once when the paper copy got lost or faded.
Paperwork will make or break your claim
Miss one document and your whole claim can fall over. Police reports, airline reports, original receipts. Keep everything. We learned this the hard way after the bag theft in Italy. No report, no proof, no claim.
Insurance covers disasters, not bad luck
Here’s the truth most people don’t get told upfront. Travel insurance isn’t there to cover every mistake or grey area. It’s built for the black and white stuff. If you ignored medical advice, travelled with symptoms, or went against a government warning, insurers will use that against you. If something looks foreseeable, they can and will exclude it.
Our take
Travel insurance can feel like a maze of clauses and conditions. It’s one of the non-negotiables when we plan any trip, including the long term travel we’re planning next year. We’ve hit plenty of them ourselves, from a stolen bag to hospital visits in three different countries.
It’s frustrating at times but knowing what you’re covered for, and what you’re not, saves you a lot of grief later. Read the terms before you go. Keep your paperwork. Don’t assume common sense and insurer logic are the same thing when it comes to travel insurance policies.
At the end of the day, travel insurance is essential, not optional. Don’t let the fine print put you off. Understand your policy, then go enjoy the trip.
We’ve been giving straight-up travel advice for midlife couples for over 26 years. Take a look at the story behind Street Eats & Window Seats.
How do I know if my travel insurance is any good?
Honestly, you don’t, not until you actually need to claim on it. We’ve made claims in Germany, Cambodia, Vietnam, Bali and Italy over the years and each one taught us something different about how insurers actually operate versus what the brochure says.
What counts as an unattended item on a travel insurance claim?
More than you’d expect. A bag under a cafe table, a phone on a beach towel, even a backpack on a train luggage rack can all be classed as unattended. Insurers use this to argue you didn’t take reasonable care, which can be grounds to deny a claim.
Will travel insurance replace stolen items at full value?
No. Most policies depreciate the value of stolen or lost items. A camera worth $1,200 a couple of years ago might only get you $800 or $900 back. Don’t expect a like for like replacement.
Does travel insurance cover pre-existing medical conditions?
It depends on the condition and whether it’s declared. Pre-existing conditions cover more than serious illness. High blood pressure, anxiety and ongoing back pain can all fall under this. If a claim can be linked to a condition you didn’t declare, it can be denied.
Does drinking alcohol void a travel insurance claim?
It can. Most policies don’t require you to be drunk for a claim to be denied. If alcohol played any part in the incident, that alone can be enough grounds for the insurer to reject it.